Next Generation Financial Technology
Quant Finance
Asset Optimization
Software Engineering
Data Modeling
Mission
Valdon Group is a supplier of financial technology located in the center of Zurich, Switzerland. The company translates current research, expertise and technology into consulting and software services for regulatory compliance and decision making in the financial industry. Its repertoire covers autonomous advisory systems, model validation, model development, portfolio optimization, market making, risk evaluation and assessment, as well as data science, statistical inference, machine learning, artificial intelligence and blockchain. The team specializes in end-to-end software design and development for financial technology firms and complements it with technology and quantitative finance consulting.
Services
Model Building
Develop, build, and implement
Valdon develops and implements large-scale risk and trading models that assess and forecast business quantities from time series: rating tools, value-at-risk and expected shortfall forecasts, quantile predictions, and dynamic margin models for exchanges and clearing houses. The work draws on current research in univariate and multivariate time series modeling.
Data Analytics
Big data and machine learning in practice
Data accumulated across departments, systems and entities is a substantial resource. Combining it sharpens decisions and refines business processes. Valdon contributes the statistical expertise, partnerships and technology to integrate, analyze and process large data sets, including current methods of machine learning.
Optimization
Methods and implementation
Optimization is central to understanding complex systems. Valdon solves optimization problems in statistics, econometrics and related fields such as bioinformatics and computer vision; in finance, these include risk management, option pricing, high-frequency data analysis and portfolio optimization. Modern optimization methods are developed in-house and delivered together with their technical implementation.
Model Validation
Regulatory compliance
Regulatory compliance is increasingly demanding and a competitive factor. As regulators require better analytics and more frequent reporting, banks, insurers and other financial institutions validate their internal risk and trading models continuously. Valdon provides validations for a broad spectrum of risk models, including variance, value-at-risk, expected shortfall, portfolio downside risk, time series risk factors and rating tools, tailored to individual requirements.
Fintech Platform
Since 2016, Valdon has been digitalizing financial technology firms end to end. We design and build infrastructure and applications and operate them as required. We write the software, and it remains the property of our clients. We take care of your technology while you run your business. Get in touch today.
Application journeys
Onboarding flows for direct and broker business, featuring custom white-label integrations for external brands and fully automated credit top-up functionalities to drive customer retention.
Affordability calculation
Proprietary budget calculation engine for the Swiss market, processing complex income and cost metrics to deliver compliant affordability assessments for personal loans and leasing.
Credit-bureau workflows
Integrating ZEK workflows and reporting into core banking systems, including the implementation of credit bureau access via CRIF and Intrum.
Credit assessment
Scoring dashboards and workflows that enable intermediary credit teams to assess every application consistently.
Robo-advisory
Analyzing risk measures of stocks, crypto and other assets to optimize and rebalance client portfolios in alignment with their risk profiles.
Liquidity provision
Liquidity across the full order-book depth, with bid and ask pairs per trading amount that follow the order books of reference exchanges.
Customer documents
Automated document generation engine that dynamically creates PDF contracts, terms, account statements, and dunning letters based on system triggers.
Financial transactions
Payments and disbursements transferred and verified between bank accounts and client-side systems in both directions, ensuring full reconciliation and transactional security.
Market making
Order book automation and market tracking across exchanges, with time series models that keep spreads and inventories balanced.
Quantitative modeling
Model development, estimators and data sources, with out-of-sample backtesting, scenario simulation and hedging strategies.
Data governance
Data modeling and management for the credit business, including comprehensive reporting for all stakeholders, refinancing institutions, and business partners.
Banking infrastructure
Integration with core banking systems like Mambu and Abacus, deployed as microservices, back-end solutions, or within partner systems.
Working with Valdon, better now than later
Build on time and material
You own the software
Valdon builds your platform to your specifications in close collaboration with your managers and teams. You define it, we make it. The software belongs to you outright, and Valdon can continue to operate and develop it on your behalf.
Valdon platform as a service
Shortest path to launch
License Valdon's own platform as a white-label solution under your brand, built from components that run in production. Hosting in a Swiss cloud, or in the client's own IT infrastructure; development costs are shared across clients.
Senior-only team
Experience on every task
Exclusively senior professionals and specialists, each with C-level experience. The partners hold doctorates in banking and finance from the University of Zurich, and Valdon sponsors the university's start-up seminar Banking and Finance 2.0.
Entire IT landscape
Beyond the fintech stack
Comprehensive IT architecture around the fintech platform, hosted in a Swiss cloud or on premises in the client's own IT infrastructure.
Management as a service
Leading the way
Senior leadership roles (e.g., CPO, CTO, CRO, CIO) as a service or as consultancy in the build-up or growth phase of your business.
Bank-grade data
Ready for due diligence
Risk modeling, model validation and reporting to refinancing banks keep loan-level tapes sound under due diligence.
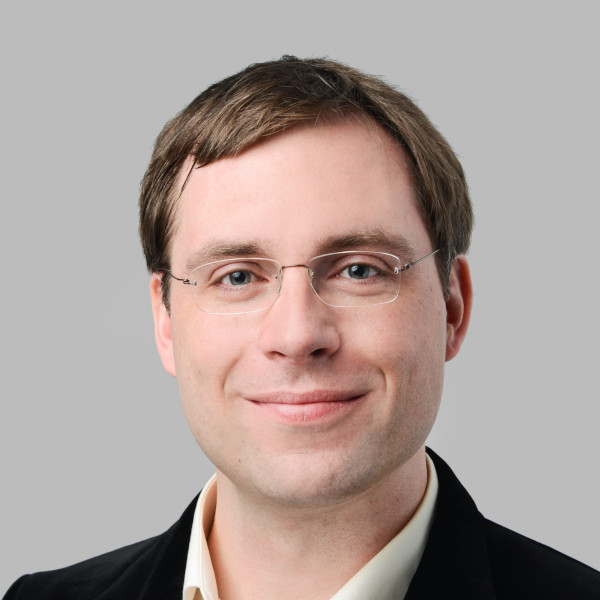
Jochen has a track record of academic research of more than ten years since his first MSc in Economics at the University of Kiel, Germany. In addition, he holds a MSc in Computer Science from the University of Kiel, and a PhD in Finance from the University of Zürich. He worked as Senior Research Associate at the Department of Banking and Finance of the University of Zürich, supported by the Swiss National Science Foundation, for years. Other positions cover portfolio management (robo-advisory), and data science (retail). His background is in computer vision, statistics, data analytics, time series analysis, econometrics, risk modeling, and portfolio optimization. Jochen is a passionate developer and specialist for large-scale optimization problems and model development. He is Co-Founder of Valdon Group, and our Head of Operations.
Sven has decade long extensive experience in the financial services industry after his graduation at the University of Kiel, Germany, of what would be nowadays called a MSc in Data Science. He continued with working for the Department of Banking and Finance at the University of Zurich and then moved on to become an exotics trader at JPMorgan's equity trading floor in London, mostly involved in hybrids derivatives trading and hedging. The entrepreneurial spirit of Dr. Steude led him further to quantitative consulting in the area of risk prediction for various trading firms, clearing houses, hedge funds and quant consulting firms, and one of which he now co-founded himself (2015). Dr. Steude holds a PhD in Econometrics from the University of Zurich, Switzerland. For more than seven years now, he is leading the Hackaton and the 'Banking and Finance 2.0' start-up seminar of the University of Zurich (Department of Informatics and Department of Banking and Finance), where he is also a senior lecturer in Options-Trading and Statistics and Econometrics.


